

What is a Lifetime ISA?
 Lucy Wilmott
If you’re saving for your first home or thinking ahead to retirement, a Lifetime ISA (LISA) could help boost your savings with a free 25% government bonus. But how does it work, and is it the right choice for everyone?
Key Takeaways
- 25% government bonus: Get a £1 bonus for every £4 you save, up to £1,000 per year.
- Eligibility: You must be aged 18–39 to open an account and can save until age 50.
- Usage: Funds must be used for a first home (up to £450,000) or retirement (age 60+).
- 12-month rule: The account must be open for at least 12 months before you can use the bonus for a home.
- Withdrawal penalty: A 25% government charge applies if you withdraw for other reasons, potentially returning less than you put in.
What is a Lifetime ISA?
A Lifetime ISA (or LISA for short) is a type of ISA savings account designed to help you save for your first home (worth up to £450,000) or retirement from age 60. You can save up to £4,000 per tax year in a LISA, and the government will add a free 25% bonus. That means you could get up to £1,000 top-up for free each tax year! Plus any interest you earn if you save into a Cash Lifetime ISA - and as it’s an ISA, that interest is tax-free!
- Who can open a Lifetime ISA? You need to be aged 18 - 39 to open a Lifetime ISA, and be a UK resident (more on this below)
- When can I use my LISA savings? You can use your LISA funds for an eligible house purchase, or for retirement on or after your 60th birthday. There's also an exception if you're terminally ill with less than 12 months to live. If you withdraw the funds for anything other than these reasons, you'll be hit by the withdrawal penalty (details below)
- How long do I need to have a LISA? You must have had your Lifetime ISA open for a year to use it (and the government bonus) towards your first home purchase. This time starts from when you first pay into the account.
Withdrawals from a Lifetime ISA for any purpose other than buying a first home (up to a value of £450,000) or for retirement (60+) incur a 25% government penalty, meaning you may get back less than you paid in. Tax treatment depends on individual circumstances and may be subject to change in the future
Is a Lifetime ISA right for you?
A Lifetime ISA could be a great way to give your first-home deposit a boost, provided you’re confident you’ll use the money for an eligible property purchase or keep it saved until retirement.
How does a Lifetime ISA work?
You can save up to £4,000 per tax year into a Lifetime ISA, and the government will add a free 25% bonus (up to £1,000 a year) on top of whatever you save. So if you save £1,000, you’ll get a free £250 top-up; save the full £4,000, and that’s a free £1,000 added to your pot. It's worth noting that the £4,000 LISA limit counts towards your overall annual ISA allowance of £20,000 (for the 2026/27 tax year). So if you max out your LISA, you can still put up to £16,000 into other ISAs that year. You’ll also earn interest on your savings if you open a Cash Lifetime ISA, or potential investment growth if you open a Stocks & Shares Lifetime ISA.
You can only use your Lifetime ISA funds to purchase your first home or to fund retirement. Your home purchase must meet certain criteria, such as being below £450,000 in value and your first home anywhere - not just in the UK. It's also worth knowing that you can hold cash or stocks and shares in your Lifetime ISA, or a combination of both, depending on what suits your goals.
You can save up to £4,000 annually until age 50, and the bonus is paid every month that you pay into the account. You’ll only get the bonus on your own contributions, meaning the government won’t add the 25% bonus to interest or investment growth.
Important
You’ll pay a 25% withdrawal charge if you take money out for anything other than buying your first home or retirement. This means you could get back less than you put in. With a Stocks & Shares Lifetime ISA, capital is at risk, past performance is not a reliable indicator of future results.
Who can open a Lifetime ISA?
You can open a LISA if you’re a UK resident aged 18 to 39. Crown servants, such as members of the armed forces serving abroad, are also eligible. If you’d like to use your Lifetime ISA to buy your first home, you’ll also need to be a first-time buyer. If you’ve already owned property either in the UK or abroad, you can use a Lifetime ISA for retirement.
If you don’t want to use a Lifetime ISA for retirement, or you’re not a first-time buyer, you might want to consider a Cash ISA instead. You’ll still earn interest tax-free, but you won’t get the 25% government bonus when buying a property.
By saving into a Lifetime ISA instead of enrolling in or contributing to a pension, you may lose out on contributions by an employer (if any), and it may affect your entitlement to means-tested benefits
What types of Lifetime ISA are there?
There are two kinds of Lifetime ISAs. A Cash Lifetime ISA is a savings account that earns interest (tax-free). Ideal if you plan to buy a home within the next 3–5 years.
With a Stocks and Shares Lifetime ISA, your money is invested in the stock market, which means the value of your LISA savings can rise and fall over time. Stocks and shares tend to outperform savings in the long term (although this isn’t guaranteed), making a Stocks & Shares Lifetime ISA a potentially better choice if you’re using it for retirement. However, it also comes with more risk, and there’s no guarantee that you’ll get back what you put in.
It's also possible to hold a combination of both cash and stocks & shares within a Lifetime ISA, giving you the flexibility to split your savings based on your timeline and risk appetite.
Capital at risk. Past performance is not a reliable indicator of future results.
Who offers a Lifetime ISA?
Several UK providers offer Lifetime ISAs, but interest rates vary significantly. Here is how Tembo compares:
| Provider | Interest Rate (AER) | Added Benefits |
|---|---|---|
Tembo | 4.30% (Variable) | Fee-free mortgage advice & Best Deal Guarantee |
Moneybox / Plum | Lower | N/A |
Skipton Building Society | Significantly Lower | N/A |
Plus, as a savings customer, you’ll also have access to Tembo’s award-winning mortgage service fee-free when you come to buy your first home, and the Best Mortgage Deal guarantee*.
Are Lifetime ISAs worth it?
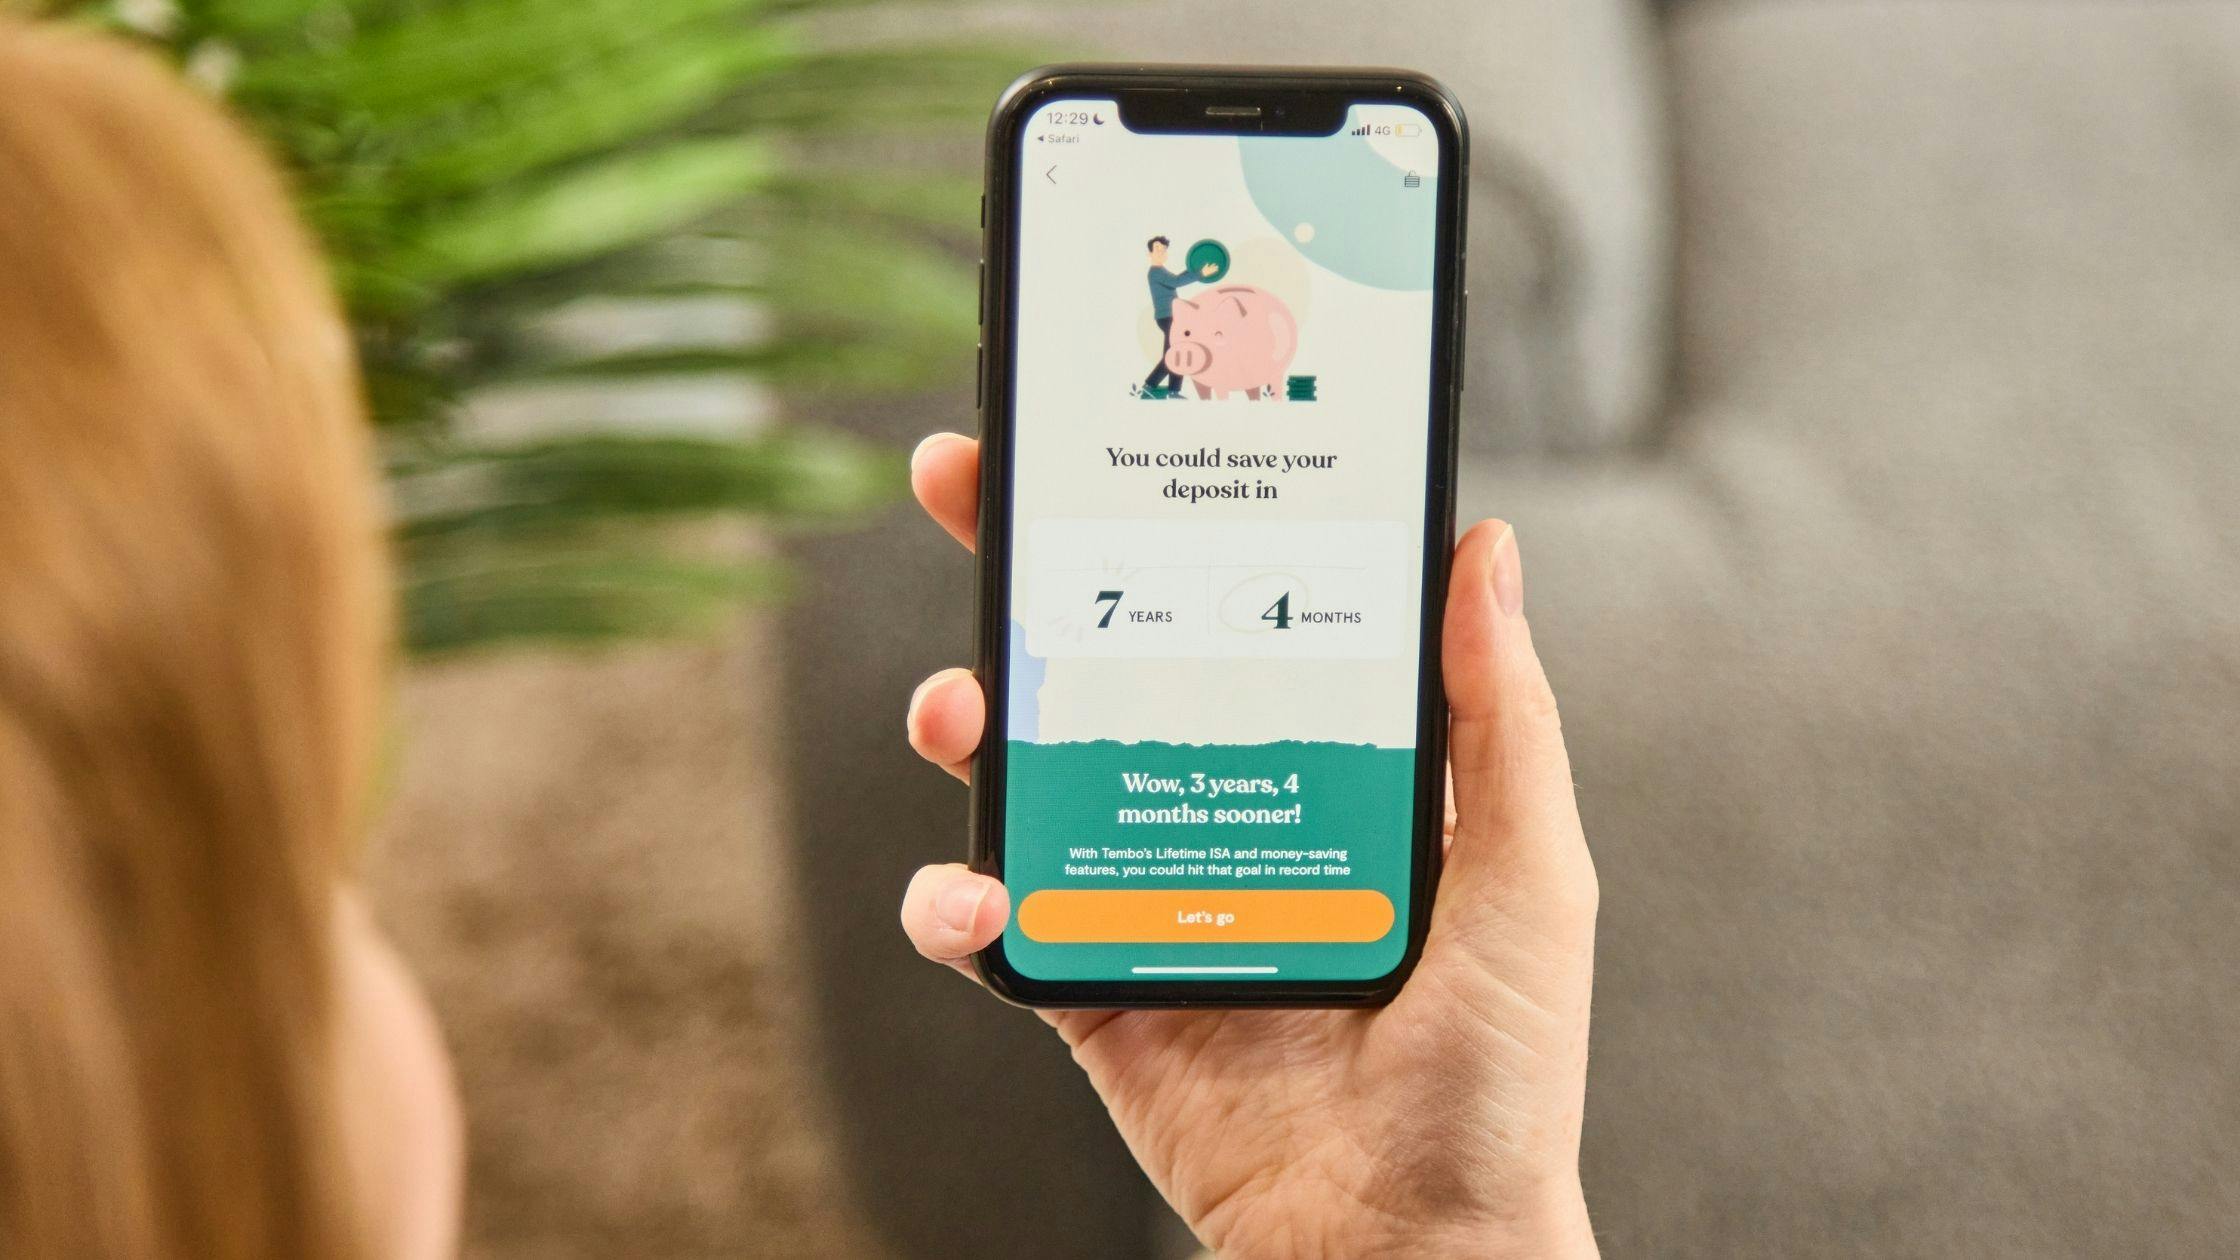
If you’re saving for your first home and meet the criteria, a Lifetime ISA can be a great way to boost your deposit and buy a home sooner. Research into our own customer data showed that first-time buyers who use a Lifetime ISA are able to buy their home four years earlier than those who do not. But many first-time buyers are missing out, as only 1 in 6 use a Lifetime ISA. This is because people don’t know that this type of ISA savings account is available to them, or they are worried about the withdrawal charge if they take money out for anything other than their first home purchase or retirement.
However, Lifetime ISAs are an incredible savings vehicle that could help you save up a house deposit years faster. It’s the only savings account that gives you a free 25% government bonus, and because it’s an ISA, you’ll also earn tax-free interest. As long as you only put money into the account you won’t use in emergencies, then it could be a worthwhile choice for many aspiring first-time buyers.
"The Lifetime ISA is a really effective way to reduce the time it takes to purchase your first home. With minimal government support announced in the recent budgets for homebuyers, LISAs offer young people a great opportunity to access much needed additional funds to bolster their deposit"

Richard Dana
CEO of Tembo
Learn more: What is an ISA?
Are Lifetime ISAs worth it?
If you’re a first-time buyer, a Lifetime ISA can help your deposit go further with a 25% government bonus, provided you’re comfortable with the withdrawal rules.
What are the downsides of a Lifetime ISA?
While a Lifetime ISA offers major benefits, there are a few limitations to consider:
1. The property cap might limit your options
If the home you’d like to buy costs more than £450,000 or it will do by the time you finish saving, the property won’t be eligible for the LISA bonus. This means you’ll need to:
- Buy somewhere cheaper
- Pay a 25% penalty on the amount you withdraw, or
- Leave your savings in your Lifetime ISA until you turn 60
However, from our own research, we found that 97% of Lifetime ISA customers were buying an eligible home under the £450,000 price cap!
2. The 25% penalty for ineligible withdrawals
Any money you put into your Lifetime ISA should only be for your first home purchase or retirement. This is because if you take money out of your Lifetime ISA for any other reason, this will be classed as an ineligible withdrawal, and it’ll leave you with less money than you put in. That’s because not only does the 25% penalty take away any government bonus you’ve earned, it also deducts 6.25% of your initial deposit. The only other exception is if you are terminally ill with less than 12 months to live, in which case you can withdraw penalty-free.
To avoid this, any money you might need - for example, for emergencies, or travelling - put into a different account so you aren’t dipping into your Lifetime ISA for these costs.
Learn more: When can I withdraw from my Lifetime ISA?
3. Stocks & Shares LISAs come with investment risk
Cash LISAs are generally safer if you plan to buy in the next few years, but over the long term, money invested in the stock market tends to outperform savings. But this isn’t guaranteed. Like all investments, there is a risk the value of your investments will go down as well as up.
Lifetime ISA FAQs
How long does a Lifetime ISA last?
You can open a LISA between 18 and 39, contribute until you’re 50, and use the funds from age 60 (or sooner for a house).
Is a Lifetime ISA free money?
In a way, yes. For every £4 you save, the government gives you £1, up to £1,000 a year. But you must use the money for a first home or retirement to avoid penalties.
Can I have more than one Lifetime ISA?
Yes, but you can only contribute to one Lifetime ISA per tax year. You can also transfer your Lifetime ISA to another provider, for example, to get a better interest rate.
Does the Lifetime ISA count towards the annual ISA allowance?
Yes. The £4,000 annual LISA limit counts as part of the overall £20,000 ISA allowance for 2026/27. Maxing out a LISA leaves up to £16,000 for other ISA products in the same tax year. The government bonus does not count towards the allowance.
Can I have a Help to Buy ISA and a LISA?
Yes, but you can only use the government bonus from one of them when buying your first home.
Can I transfer a Help to Buy ISA into a LISA?
Yes, but it is not a direct transfer because they are different account types. The money you move counts towards the £4,000 Lifetime ISA allowance for the tax year, so if you have more than £4,000 in your Help to Buy ISA, you’ll need to move it across multiple tax years.
Before making the switch, take a look at our Lifetime ISA vs Help to Buy ISA guide, where we weigh up the pros and cons of each.
Can two Lifetime ISAs be used to buy a house together?
Yes, you can use two Lifetime ISAs to buy a house as long as you’re buying the property with someone else who is also a first-time buyer. So if you and your partner are buying a house together and you have a Lifetime ISA each, maxing out your accounts for 5 years would see you getting a total of £10,000 off the government towards your first home.
Is the Lifetime ISA being discontinued?
Yes, the government has announced the LISA will be replaced by a new First-Time Buyer ISA in April 2028. However, anyone who already has a LISA can carry on paying into it beyond that date. Opening one before April 2028 locks in access to the 25% bonus for as long as the saver is eligible. See our blog post here.
Can someone who is not a UK citizen open a Lifetime ISA?
Yes, eligibility is based on residency, not citizenship. Anyone aged 18 to 39 who is a UK resident can open a LISA regardless of nationality. US citizens living in the UK would qualify, though US tax rules around ISAs can be complex, and specialist advice is recommended.
Can I use a Lifetime ISA for a house deposit and retirement?
Yes, you can use a Lifetime ISA for both a house deposit and retirement. However, be aware that when you use your Lifetime ISA for a house purchase, if you withdraw all the funds your provider may automatically close your LISA account, but you can usually open another one if you’re still under 40. Also, while a LISA can be a good supplement to a pension for many, it is not a replacement, as you may miss out on employer contributions to a workplace pension scheme.
If you’re struggling to save a full deposit or pass affordability checks, there are other ways to get on the ladder. At Tembo, we specialise in a range of mortgage products and budget-boosting schemes designed to boost your buying power, such as:
- Deposit Boost. A family member can release equity from their property to top up your deposit.
- Savings as Security. Also known as a springboard mortgage, this lets a loved one place savings into an account linked to your mortgage as security.
- Income Boost. Add a parent or family member to your mortgage to increase how much you can borrow. They don’t need to be on the property title.
What if I use my Lifetime ISA for retirement?
You can use your LISA for retirement if you don’t end up buying a home. The 25% bonus continues until you’re 50, and you can access the funds from age 60 without penalty. Your money will continue to earn interest (in a Cash LISA) or investment returns (in a Stocks & Shares LISA) in the meantime.
Many self-employed people use a Lifetime ISA as a way to save for later life, especially if they don’t have a pension through work. A LISA can feel more flexible because the money can be accessed earlier if needed, although taking it out for anything other than an eligible first home purchase, retirement from age 60, or terminal illness will trigger the withdrawal penalty.
The tax treatment is also different. With a Lifetime ISA, contributions are made from post-tax income and withdrawals from age 60 are tax-free. With a pension, contributions usually benefit from tax relief on the way in, but withdrawals are taxed in retirement. This means higher- or additional-rate taxpayers may find a pension more tax-efficient.
It’s also worth remembering that the normal minimum pension age is due to rise from 55 to 57 in April 2028, while Lifetime ISA funds for retirement can only be accessed from age 60. For anyone with access to a workplace pension, it usually makes sense to prioritise enough pension contributions to get the full employer match before topping up a LISA, and it may be worth speaking to a financial adviser if they’re unsure.
By saving into a Lifetime ISA instead of enrolling in or contributing to a pension, you may lose out on contributions by an employer (if any), and it may affect your entitlement to means-tested benefits.
*Fee-free mortgage advice is subject to eligibility, see terms & conditions here.
Make your first-home savings work harder
A Lifetime ISA can give your deposit a powerful boost, with a 25% government bonus of up to £1,000 every tax year. Just make sure it suits your home-buying plans before you start saving.